Hazer Group (HZR)
Original analysis
English edition of the original analysis by trademvment. Original TradingView publication ↗
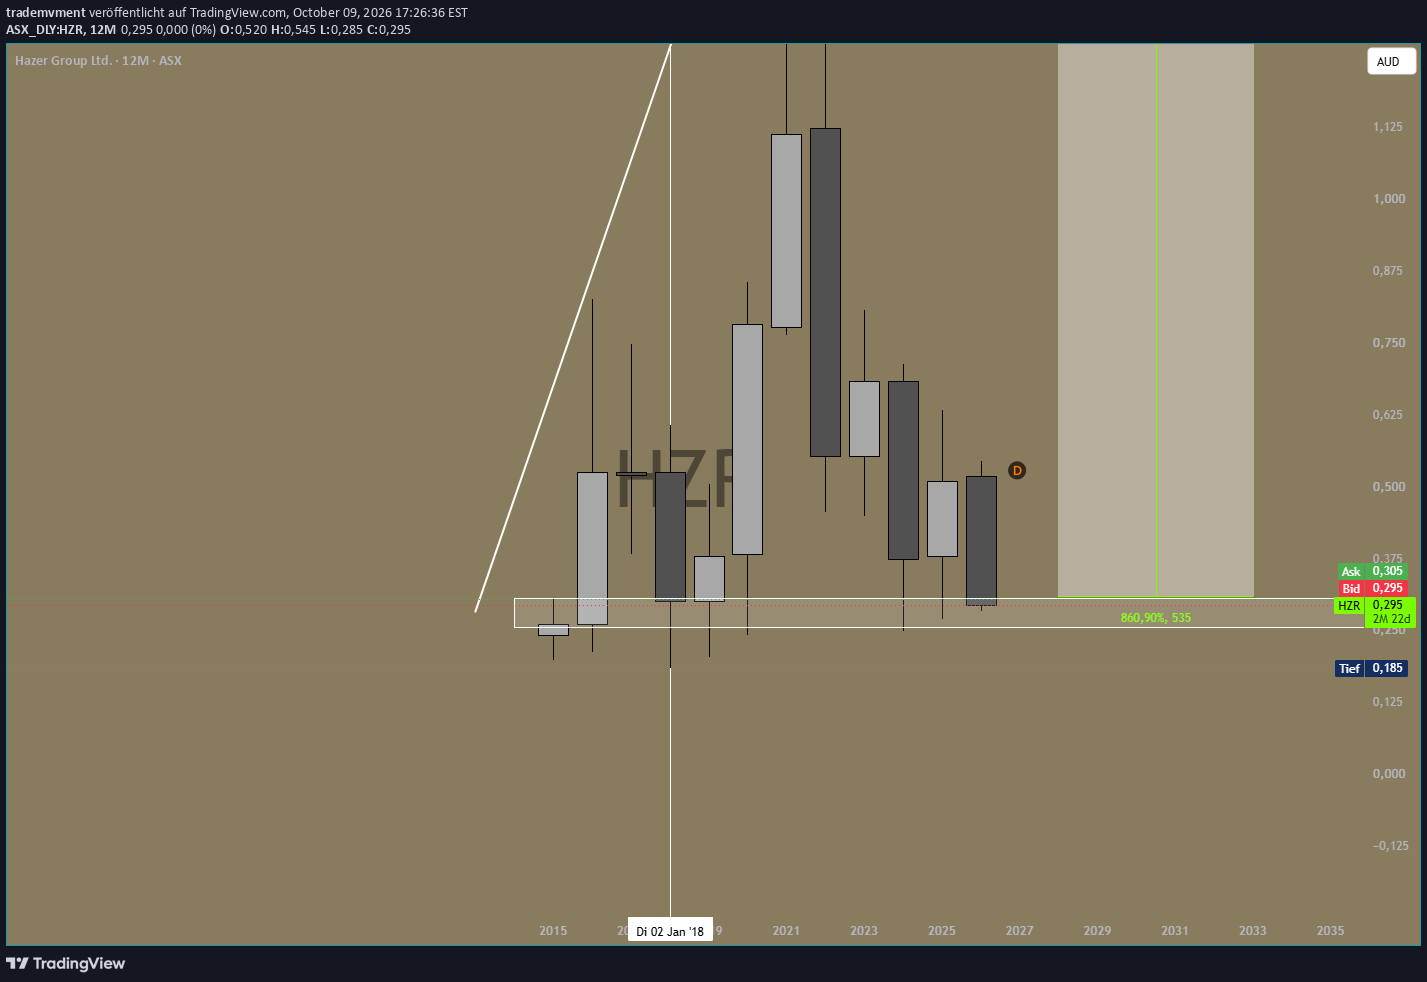
Hazer Group (HZR)
I am already positioned in Hazer Group because I see substantial long-term potential in its technology and business model. My view of the stock is bullish: a long idea with a horizon of several years.
The core of my thesis is the combination of hydrogen, graphite and a scalable licensing model. At the same time, the weekly chart shows the stock trading far below its previous highs. This combination of commercial development and a possible long-term base is what makes Hazer interesting to me.
One technology, two usable products
The Hazer Process splits methane into hydrogen and solid carbon in the form of graphite. Iron ore serves as the catalyst. For me, the economically interesting point is that one feedstock produces two potentially marketable products.
Hydrogen can be used in industry and energy supply, for example. Graphite opens up additional markets, such as building materials, the steel industry and, subject to suitable quality, batteries. The revenue generated depends on product quality, customers and production costs.
The potential sale of graphite could improve the economics of hydrogen production. That is an important part of the idea for me: the second product stream can create additional value.
The opportunity lies in licensing
The technology is intended to reach further markets through partners, engineering and licences.
If this leads to several commercial plants, Hazer could earn revenue from the use of its technology. For me, this is where the greater long-term potential lies: a developed technology can be deployed at different sites.
The international projects and paid studies show that industrial partners are already engaging with the process. On 17 August 2026, for example, Hazer announced a paid preliminary study with a major Japanese energy utility. It examines potential plants producing 30,000 and 300,000 tonnes of hydrogen per year, respectively.
Gas, China and the Australian dollar
Uncertain energy supply and fluctuating gas prices form part of the background to this idea. Going into the new year, I expect oil and gas prices to be substantially above their current levels.
Higher gas prices are not an automatic advantage: methane remains a feedstock and affects production costs. What interests me is the value created from gas and industrial demand for the process.
China and AUD: I expect a weaker Chinese economy and a stronger US dollar. Lower demand for Australian commodities could put additional pressure on AUD.
For Hazer, the interesting implication would be that international revenue in US dollars could be worth more Australian dollars when converted. This depends on the relevant contract currencies. At the same time, a weaker AUD can make imported components more expensive.
A cooling Australian economy could also put interest rate cuts back on the agenda later. Cheaper financing would help large industrial projects and could make implementation of Hazer's technology easier. I think the labour market could weaken further and that Australia may finally take the step towards cutting interest rates.
Weekly, yearly and targets
In the attached weekly chart, HZR is trading at around AUD 0.295. The area around AUD 0.30 is the starting zone of my marked long idea.
The yearly chart is the reason for my entry. I think there is still good potential to buy it while it is undervalued.
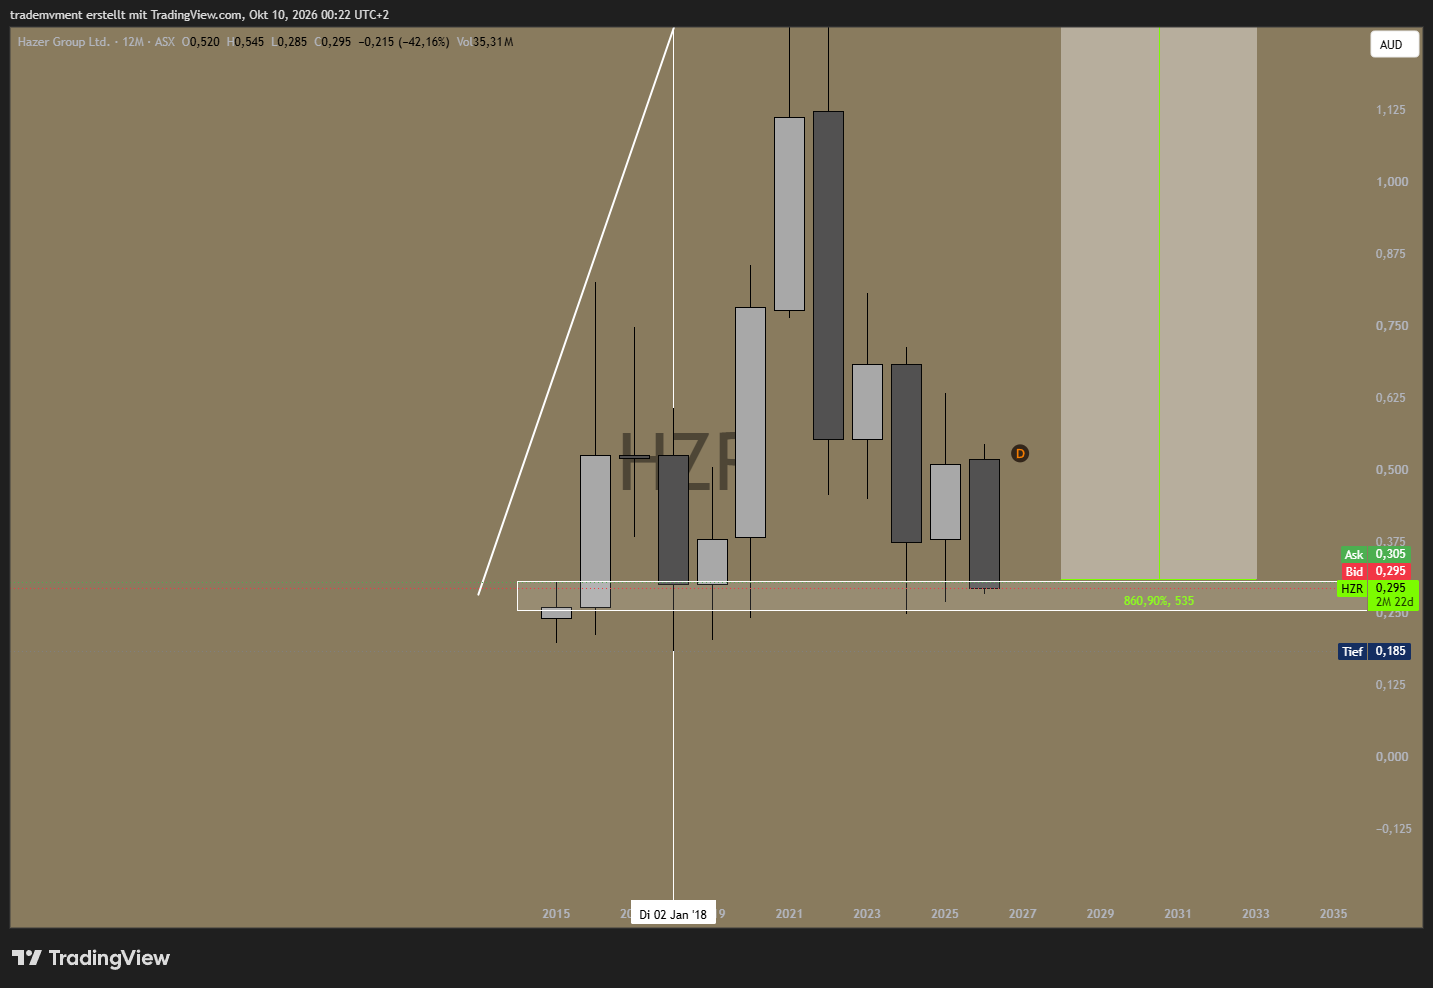
If there is a sustained revaluation, I initially see the previous high around AUD 1.835, followed by the Fibonacci level at AUD 1.97, as broader reference zones.
For the long-term bullish scenario, my marked target zone is AUD 3.00 to AUD 3.63, with AUD 3.32 as an intermediate level. These areas come from the technical projection in the chart. They are not calculated company valuations and have no fixed target date.
My direction: long term, long
I want to be positioned ahead of the possible transition from studies to commercial plants and recurring licence income. If Hazer makes that transition, the market could value the company very differently. The combination of two product streams, KBR as a licensing partner and concrete interest from industrial customers underpins my bullish view.
Company information and announcements:
- Hazer Group projects
- Hazer Group announcements
- KBR: Meeting growing demand through methane pyrolysis technology
Australian monetary policy at the time of publication:
Transparency note: The trading idea and my market assessment are based on my own research. AI was used to polish the language, structure the text clearly and cross-check individual facts.
Loading comments…