Yara International (YAR) Short
Original analysis
English edition of the original analysis by trademvment. Original TradingView publication ↗
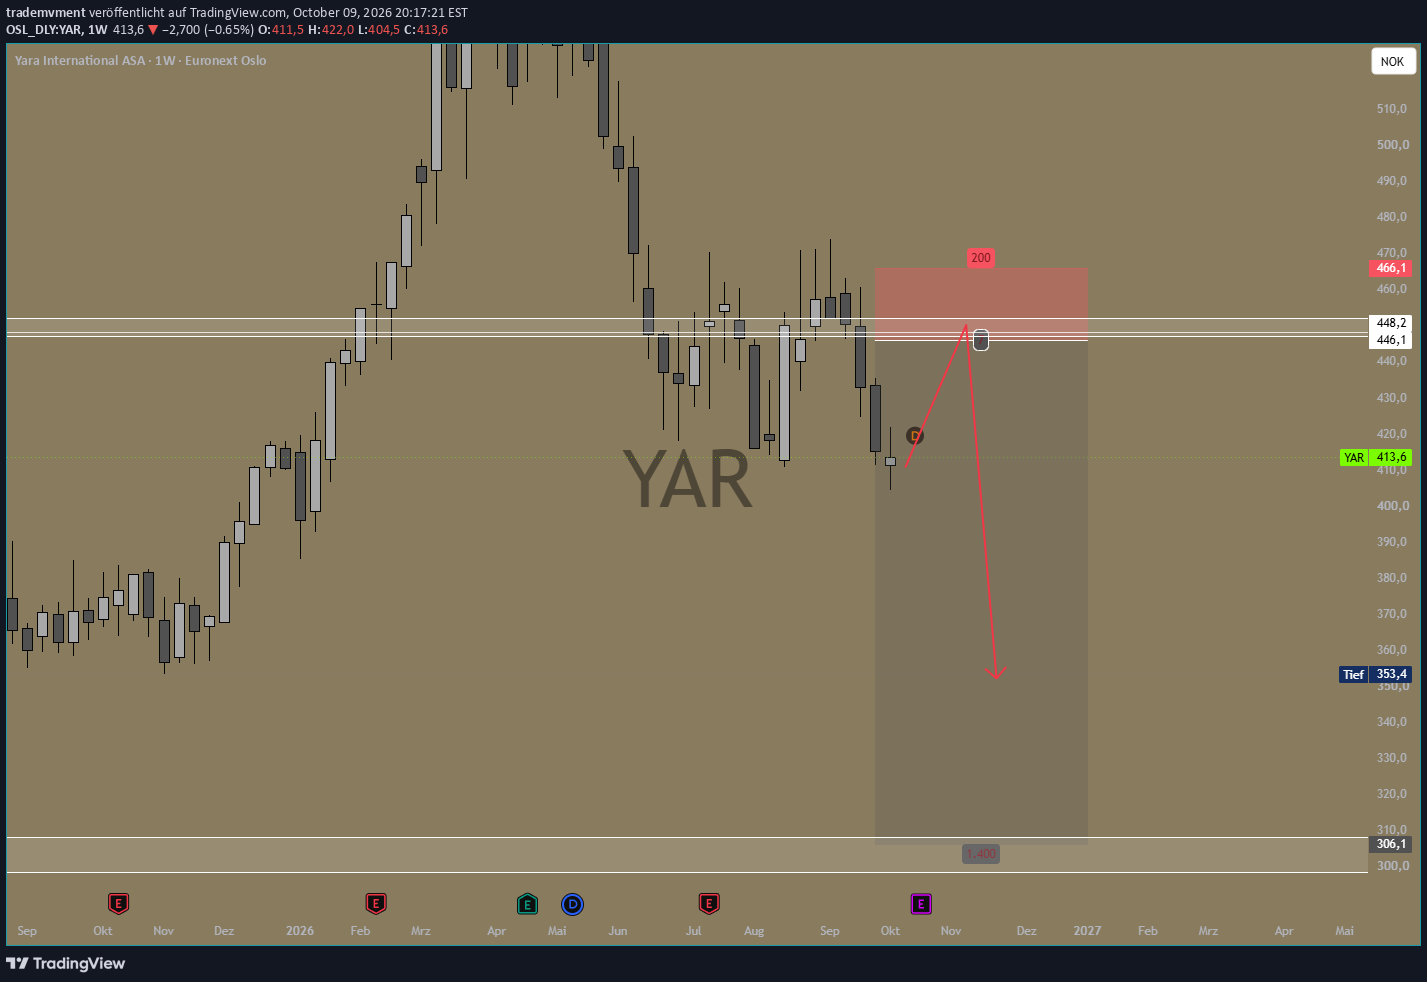
I see further short-term downside potential in agricultural commodities such as wheat, corn and soybeans. This is why I am also interested in shorting Yara.
The chain
Falling agricultural prices = declining revenue and margins for farmers = agricultural profitability goes brrr = increasing cost pressure = fewer fertiliser purchases = weaker demand = Yara's money stops rolling in and starts falling instead.
The second crucial factor: natural gas
Natural gas is a central cost factor in nitrogen fertiliser production.
If agricultural prices and, consequently, fertiliser prices fall while natural gas prices remain elevated, Yara could come under substantial pressure from both sides.
Because when sales revenue goes BRRR (the less enjoyable kind of BRRR) and production costs stay high, margins do not look good.
As a result, EBITDA, earnings expectations and, let's say, the stock's valuation could start to struggle.
The market could underestimate the effect of declining agricultural profitability on fertiliser demand.
So I am shorting it.
Loading comments…